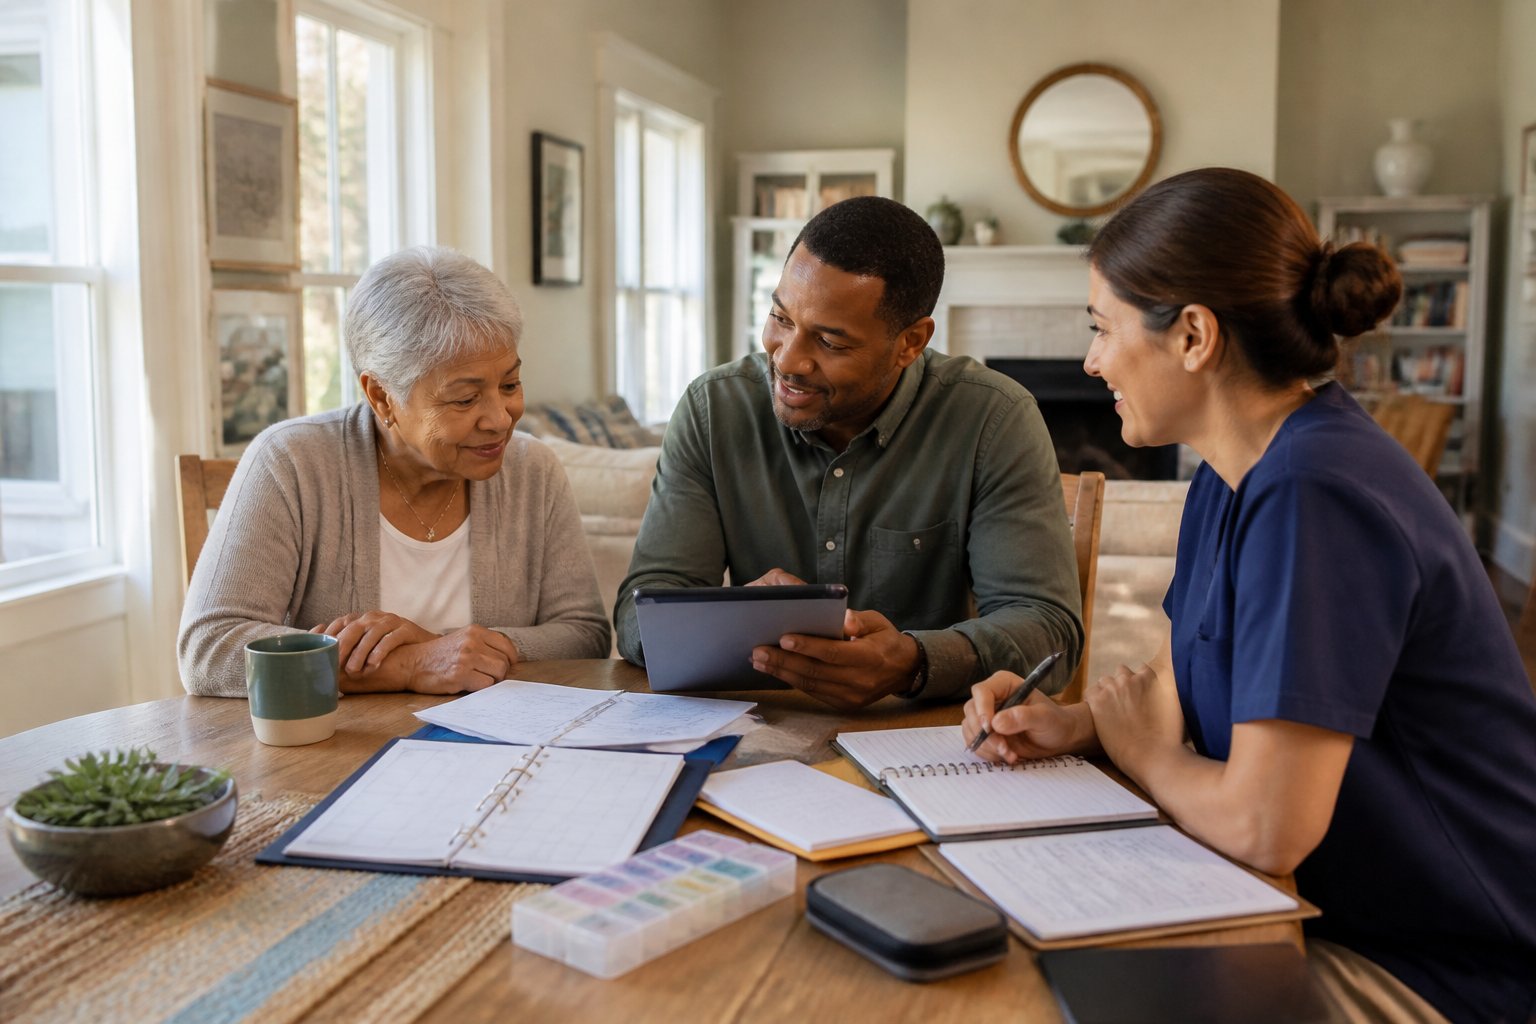
You are keeping track of your mother's medications on the back of an envelope. Your brother texts to ask when her next appointment is, and nobody knows. Somewhere between the pill organizer and that envelope, it hits you that the whole family is guessing. A personalized care plan for an aging parent at home is the fix for that guessing, and you can build it yourself.
Some families reach this point mid-crisis after a fall. Others are simply tired of repeating the same details to five different people. Either way, what helps is one clear, shared document that everyone can trust.
Keep reading to learn how to write down your parent's routines, health details, safety risks, and family responsibilities in one living plan you can update as things change. You will also see how to divide roles so no one carries this alone, and when it makes sense to bring in trained, screened caregivers. You do not have to figure this out by yourself.
Start With Your Loved One's Wishes and Current Needs
Before you write a single line of the plan, sit with your parent and ask what matters most to them. Their answers shape everything else, from bedtime to bathing to who drives them to the cardiologist.
Families often skip this step because they are in a hurry. That hurry costs you later, when your dad refuses help he never agreed to. A plan built around your parent's own words gets followed. A plan built around your fears gets fought.
What Goes Into a Personalized Care Plan for an Aging Parent at Home?
A personalized care plan is one document that holds your parent's daily routine, personal care needs, medical details, safety risks, and family contacts in a single place.
Think of it as the answer key anyone would need if they walked into your parent's home tomorrow. A visiting cousin. A new caregiver. A paramedic.
Keep one printed copy in a labeled binder near the kitchen, plus a digital copy in a password-protected document or app that only the people who need it can open. Paper works when the Wi-Fi does not.
Talk About Independence, Priorities, and Future Preferences
Ask direct questions and write down the answers word for word. What would you never want to give up? Who do you want making decisions if you cannot? Where do you want to live if things get harder?
Independence and safety are not opposites. The goal is keeping as much independence as possible while adding supports that head off a crisis. Grab bars in the shower protect independence. So does a caregiver who helps with dressing so your mom has energy left for her book club.
Good caregivers ask these questions too. The ones worth hiring want to know what brings your parent joy before they learn how she takes her coffee.
Assess Functional Abilities, ADLs, and Changing Health Needs
Activities of daily living (ADLs) are the basic tasks a person handles to care for themselves. Rate each one honestly: independent, needs reminders, needs hands-on help.
- Bathing and showering: Can she get in and out safely on her own?
- Dressing: Buttons, zippers, shoes, socks
- Toileting and continence: Any accidents, urgency, or nighttime issues
- Eating: Appetite, chewing, swallowing, weight changes
- Transferring: Getting out of bed, up from a chair, off the toilet
- Walking: Steadiness, cane or walker use, stairs
Then add the medical layer. List chronic conditions, cognitive decline, and any diagnosis of dementia or Alzheimer's disease. Note what each healthcare professional has said recently, in plain words.
Cognitive impairment changes the plan in real ways. Mid-stage memory loss can bring wandering risk and confusion that a standing routine can help manage.
How a Family Care Plan Differs From a Professional In-Home Assessment
The family care plan is yours. You write it, you own it, you update it. A professional in-home assessment is a separate visit where a home care agency meets your parent, learns the household, and recommends a schedule and level of support.
The two work together. Families who arrive at an assessment with their own plan already written tend to get a more precise recommendation, because nobody is reconstructing six months of history from memory.
Once you know what your parent needs and wants, the next question is how to get it all down on paper in a way your family will use.
Build the Living Plan Your Family Can Use Every Day
The plan earns its keep when it answers questions in under thirty seconds. Organize it into five clear parts: medical, daily routine, mobility and safety, social and emotional, and emergency information.
Write it in short lines. Nobody reads paragraphs at 2 a.m.
Record Medical Information, Providers, and Medication Details
Start with a one-page medical summary and update it after every appointment. List the primary care physician with phone and address, then every specialist by name and specialty.
For medications, capture name, dose, time of day, purpose, and prescribing doctor. Add allergies to medicines, foods, and environmental triggers. Note recent hospital stays with dates and discharge instructions.
A medication management app can send reminders and let family members log doses from their phones; choose one with a password and control over who can see it. In this section, note where the insurance cards, Medicare card, and healthcare proxy document are kept. If you record the actual numbers, keep that page in the printed binder or a secured file, not in an open shared folder.
Bring a printed copy of this page to every medical appointment. It can shorten visits and help catch conflicts between prescriptions from different providers.
Map a Daily Routine for Personal Care, Meals, and Sleep
Write out a normal day from wake-up to lights-out. Include wake time, personal hygiene steps, breakfast preferences, and when medications happen.
Note food restrictions, favorite meals, textures that cause trouble, and whether meal planning needs to work around diabetes or heart conditions. Write down who prepares food and how much help is needed at the table.
Sleep deserves its own lines. Bedtime, nighttime bathroom trips, sundowning, and what helps your parent settle. Caregivers who know your dad watches the 6 p.m. news before dinner can slide into that rhythm instead of disrupting it.
Consistency is what makes in-home personal care feel dignified rather than clinical.
Document Mobility Needs and Home Safety Risks
Walk the house room by room and write down what you see. Loose rugs, dim hallways, a bathroom with nothing to hold onto, stairs with one handrail.
Record mobility issues plainly: uses a walker indoors, cane outside, unsteady on the back steps, one fall in the past year. Name the rooms where falls are most likely.
Grab bars in the shower and beside the toilet, brighter bulbs, and clear pathways reduce hazards before they cause injury. Trained caregivers can spot risks families stop noticing after decades in the same house, which is part of why a fall risk reduction focus belongs in the plan from the start.
Include Social Connection, Emotional Health, and What Brings Joy
Loneliness can take a real toll on older adults' health. The plan needs a section on social interaction, emotional well-being, and mental health.
Write down who your mother likes to see, which activities she looks forward to, her faith practices, and the music that lifts her mood. Note topics or situations that cause distress so caregivers can steer around them.
Cognitive stimulation belongs here too: puzzles, photo albums, familiar recipes, singing. These small things can carry real weight, and they are exactly where companionship visits make a visible difference in someone's week.
Create an Emergency Contacts and Important Documents List
Put this page first in the binder. It should be readable by someone who has never met your family.
- Primary care physician and main specialists with direct phone numbers
- Pharmacy name, address, and phone
- Healthcare proxy and power of attorney holders with cell numbers
- Preferred hospital and any patient advocate contact
- Two family members in order of who to call first
- Location of insurance cards, advance directives, and house keys
Now that the information lives in one place, someone has to be responsible for keeping it current and acting on it.
Give Every Member of the Care Team a Clear Role
Assign a named person to each area of care and tell them they have it. Families rarely fall apart from lack of love. They fall apart because everyone assumed someone else made the call.
Six roles cover most of what a family needs to track. One person can hold two or three of them.
- Care Quarterback: primary contact for coordinating care, keeps the plan current, first call when something changes
- Medical Liaison: attends appointments, tracks medications and diagnoses, updates the medical summary
- Daily Life Coordinator: oversees the social calendar, transportation, and day-to-day well-being
- Financial and Legal Point Person: bill pay, insurance, benefits, and coordination with an attorney
- Communications Manager: sends updates, maintains the care log, runs family check-ins
- Remote Family Advocate: the voice for relatives at a distance, owns tasks that can be done from anywhere
These roles are about coordination, not control. Your parent stays the decision-maker for their own care while they are able. A healthcare proxy only steps in for medical decisions if a doctor determines your parent can no longer make them, and even then the proxy's job is to follow your parent's known wishes.
Assign Medical, Daily Life, Financial, and Communication Responsibilities
Match roles to strengths and schedules. The sibling who works in accounting takes finances. The one who lives fifteen minutes away takes daily life.
Write each name directly into the plan with a best phone number. Unwritten assignments tend to evaporate within a month.
Professional caregivers plug into this structure well when they know who to call. Ask any agency you work with how caregivers share shift notes, so the Communications Manager has real notes instead of secondhand summaries.
With roles settled, you can see where the family's own effort ends and outside support needs to begin.
Match Support to the Plan Without Taking Over
Add support in layers, starting with the smallest change that solves the problem. Home modifications first, then community resources, then professional caregivers for the tasks family cannot cover safely. This order helps protect independence, because your parent keeps doing everything they can still do well.
When Family Help Is No Longer Enough on Its Own
Certain signals mean the family plan needs professional reinforcement. Watch for these:
- Your parent needs help at hours no family member can cover
- The primary caregiver is exhausted, sick, or falling behind at work
- Bathing, toileting, or transfers have become unsafe for one person to manage
- Memory loss creates wandering risk or nighttime confusion
- Someone is driving an hour each way, twice a day, to fill gaps
Support can start at a few hours a week and grow. Some families begin with two mornings, then expand as needs change, and some eventually move toward live-in support when overnight needs appear.
How Professional Caregivers Can Follow Your Family's Plan
Hand your written plan to the agency at the first conversation. A good agency builds its care plan on top of yours instead of starting from scratch.
Caregiver quality comes down to who gets hired, so ask how caregivers are screened and trained. Consistent caregiver matching means the same person learns your mother's normal, so a lighter appetite or a foggier morning gets noticed.
Plan Ahead for Legal, Insurance, and Long-Term Care Decisions
Get the paperwork done while your parent can participate. Durable power of attorney, healthcare proxy, advance directives, and a living will belong in the binder with everything else.
An elder law attorney can sort out Medicaid rules, long-term care insurance benefits, and estate questions. The National Institute on Aging publishes free advance care planning worksheets that guide the conversation about values and treatment preferences.
Medicare covers skilled home health under specific conditions. Non-medical daily living help is a separate service, which is why families plan for it directly.
Once the plan is built and the support is in place, the work shifts to keeping it accurate.
Review the Plan Before Small Changes Become a Crisis
Put a recurring reminder on your calendar to review the plan, and update it immediately after anything significant happens. Many crises announce themselves weeks ahead in small changes nobody wrote down.
A plan that reflects last spring is worse than no plan, because people trust it.
Set a Simple Schedule for Care Plan Reviews
Pick a review rhythm your family can keep, and review more often during a period of decline or after a new diagnosis. Tying the review to a regular family call means it happens without extra coordination, and ten minutes with the document open can catch a lot of drift.
If an agency is involved, ask how its own care evaluation lines up with your family plan, so the two stay in step.
Update the Plan After Falls, Hospital Visits, or New Diagnoses
Any of these events should trigger an update as soon as you can manage it. A fall, an emergency room visit, a hospital stay, a new prescription, or a diagnosis like heart disease or early cognitive impairment.
Update medications first, then discharge instructions, then the daily routine. Recovery often changes what your parent can do for weeks, and the plan should say so.
Transitions home can be a risky stretch, which is why transitional care exists as its own service. Write down who is covering the first two weeks back.
Watch for Changes in Memory, Mood, and Daily Independence
Track trends, not single bad days. Note missed medications, withdrawal from friends, repeated stories, unopened mail, and weight loss over a month.
Caregivers who visit regularly are often the first to spot these shifts, because they see your parent on an ordinary weekday rather than a holiday. If they keep shift notes, those give you a written trail to bring to the doctor.
Emotional health deserves the same attention as physical health. A parent who has stopped calling friends needs a response as much as one with a new limp.
A Shared Plan Helps Your Loved One Stay Safe, Known, and Supported at Home
A written, shared care plan turns scattered worry into coordinated action. Your parent's routines, medications, safety risks, and wishes live in one place, and every person helping knows their role.
That structure helps aging in place work. Independence can hold longer, and the family can stop running on adrenaline and guesswork. When outside help joins the picture, trained and screened caregivers step into a household they already understand.
When you are ready to talk through what professional support would look like alongside your plan, Executive Home Care Northeast Greater Boston offers a free, no-obligation in-home assessment. You can schedule an in-home consultation online or call (855) 350-2273 to ask questions first. Bring the plan you have already built, and we will help you see what fits.
Frequently Asked Questions
What Should Be Included in a Care Plan for an Elderly Parent at Home?
A complete plan holds five things: medical details and providers, the daily routine, mobility and home safety notes, social and emotional preferences, and emergency contacts with document locations. Add the family role assignments so everyone knows who handles what. Keep one printed copy in the home and one secure, password-protected digital version.
How Often Should We Update an Aging Parent's Care Plan?
Review it on a regular rhythm your family can keep, and update it as soon as you can after a fall, hospital visit, new diagnosis, or medication change. Tying reviews to a standing family call keeps them from getting skipped. Small updates keep the document trustworthy.
What Is the Difference Between a Family Care Plan and a Home Care Agency Assessment?
Your family care plan is a document you write, own, and maintain about your parent's life and needs. An agency assessment is a visit where professionals meet your parent, review the home, and recommend a care schedule. Bringing your plan to that visit can make the recommendation more precise.
Does Medicare Pay for Non-Medical Home Care for an Aging Parent?
Medicare covers skilled home health services under specific conditions, and it does not cover ongoing non-medical help with bathing, meals, or companionship. Families typically pay privately or use long-term care insurance, veterans benefits, or Medicaid programs when eligible.